

Virginia is good motorcycle country — Skyline Drive, the Blue Ridge Parkway, and a riding season that runs most of the year. It is also a state with specific rules for riders, and a set of coverage gaps that catch people who assume motorcycle insurance works like car insurance. It does not.
What Virginia requires
Liability insurance
Motorcycles are subject to the same minimum liability limits as cars. For policies effective on or after January 1, 2025, that means:
- $50,000 for bodily injury or death of one person
- $100,000 for bodily injury or death of two or more people
- $25,000 for property damage
These figures come from the Virginia DMV and Code of Virginia § 46.2-472, and represent an increase over the $30,000/$60,000/$20,000 limits that applied through the end of 2024. Virginia also eliminated the option of paying an uninsured motor vehicle fee in place of carrying insurance.
Helmets — Virginia has a universal law
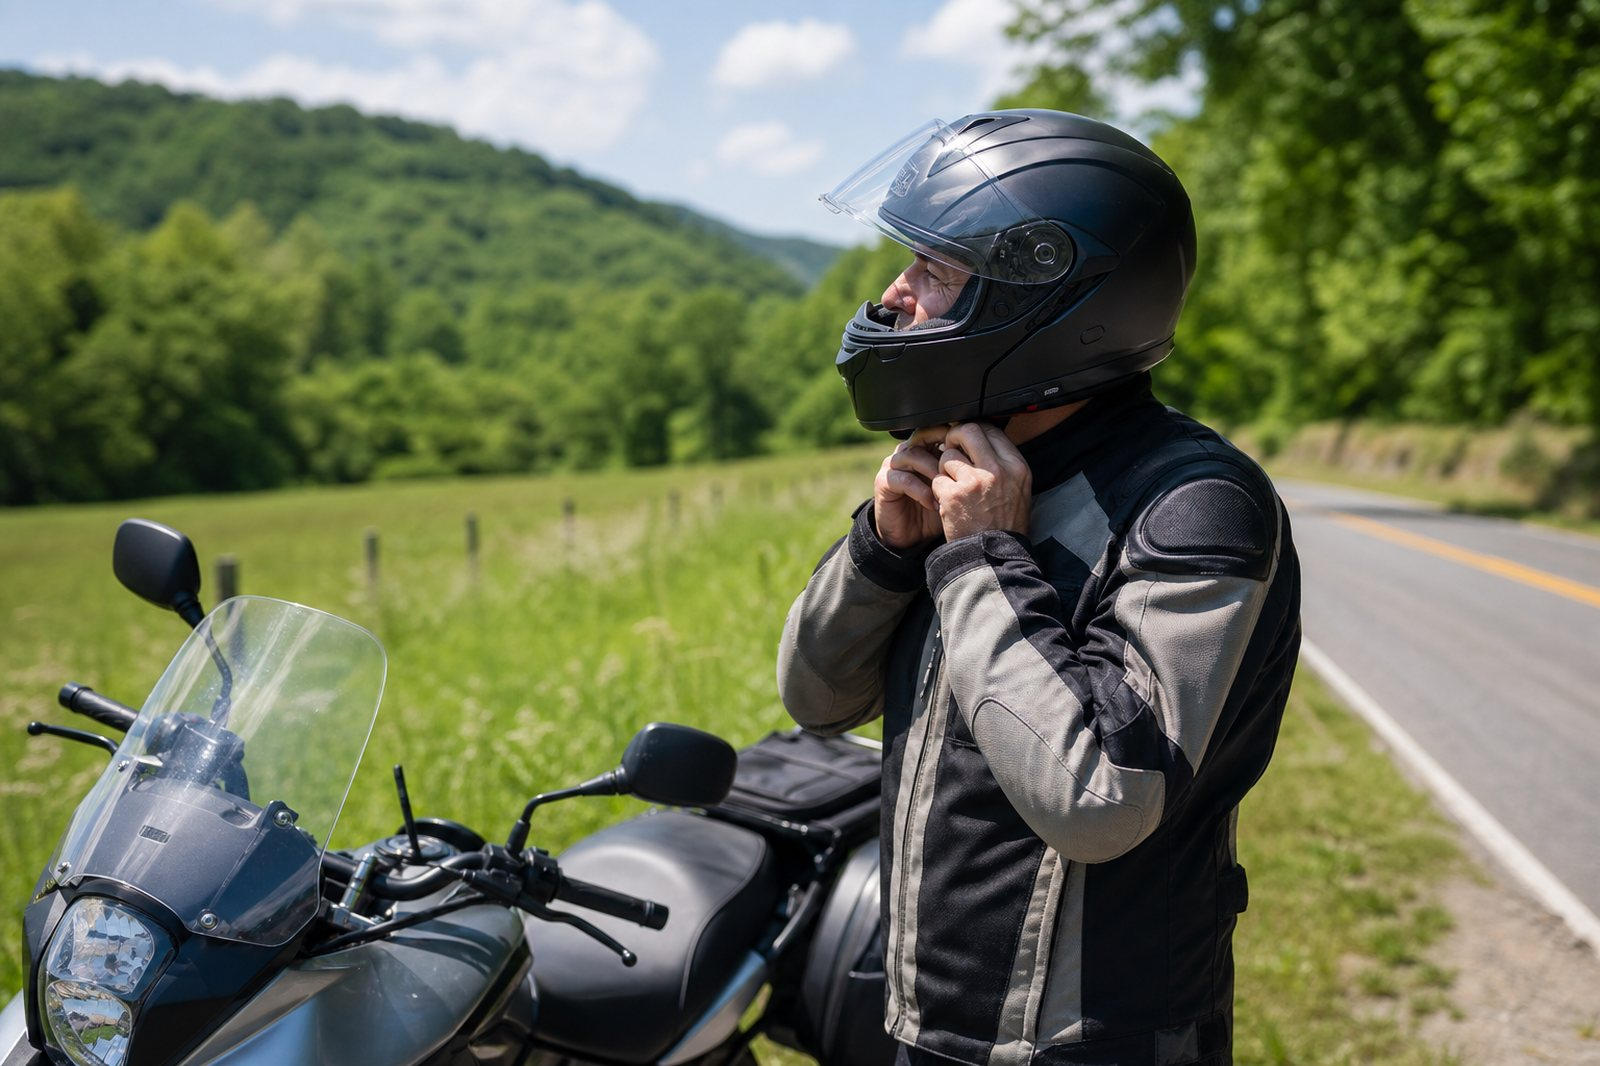
Under Code of Virginia § 46.2-910, every operator and passenger must wear a helmet meeting recognized safety standards, regardless of age or experience. Virginia is not a partial-helmet state. Riders must also have a face shield, safety glasses or goggles, or the motorcycle must be equipped with a windshield.
This matters beyond the traffic citation. In an injury claim, the question of whether protective equipment was worn can affect how a claim is evaluated.
The coverage most riders are missing
Uninsured and underinsured motorist — the important one
If we could get every rider in Virginia to change one thing about their policy, it would be this. Most motorcycle accidents involving another vehicle are caused by the driver of the car, and a meaningful share of Virginia drivers carry only the state minimum — or no insurance at all.
A serious motorcycle injury can generate medical bills that exhaust a $50,000 liability limit before rehabilitation even begins. When the at-fault driver’s coverage runs out, underinsured motorist coverage on your own policy is what pays the difference. It is typically inexpensive relative to what it protects, and it is the coverage riders most often regret skipping.
Custom parts and accessories
Standard motorcycle policies include only a limited allowance for aftermarket equipment — sometimes very limited. Exhaust systems, saddlebags, custom paint, seats, chrome, audio, and performance work frequently exceed it. If you have invested in your bike, you generally need to schedule that value specifically. Keep receipts and photographs.
Guest passenger liability
Not every motorcycle policy automatically covers injuries to a passenger on your bike. If you ride two-up, this is worth confirming line by line.
Roadside assistance and trip interruption
Motorcycle-specific towing matters — a bike requires different equipment than a car, and not every roadside plan covers it. Trip interruption coverage helps with lodging and transportation if a breakdown strands you far from home, which is worth considering if you tour.
Comprehensive — theft is the reason
Motorcycles are far easier to steal than cars. Comprehensive covers theft, vandalism, fire, and weather damage. If your bike is financed, your lender will require it regardless.
What affects your motorcycle premium
- Engine displacement and bike type. A sport bike and a cruiser of similar value can rate very differently.
- Your riding record and age, along with how long you have been licensed.
- Where the bike is garaged. Northern Virginia rates differently than rural parts of the state.
- Annual mileage and seasonal use.
- Safety course completion. Many carriers credit an approved rider safety course.
- Anti-theft devices and secure garaging.
Ways riders commonly reduce cost
- Take an approved motorcycle safety course — it can earn a discount and makes you a better rider.
- Bundle with your auto and home policies. Multi-policy credits on motorcycles are often significant.
- Ask about lay-up or seasonal provisions if you store the bike over winter. Do not drop coverage entirely — theft and fire do not observe riding season, and a lapse can raise your rate later.
- Raise comprehensive and collision deductibles if you could absorb that cost.
Talk to an agent who insures riders
McEvoy Insurance & Financial Services is an independent agency in Alexandria, Virginia, serving riders in Alexandria, Kingstowne, Franconia, Springfield, Annandale, Burke, Lorton, Arlington, and throughout Fairfax County and Virginia.
Because we are independent, we compare motorcycle carriers rather than quoting a single company — and carrier appetite for motorcycles varies more than most people expect, particularly for larger displacement bikes, custom work, and younger riders. Call (703) 642-6408 and we will review what you actually have, especially your uninsured motorist limits.
This article is general information about insurance coverage in Virginia and is not a substitute for advice about your specific situation. Coverage terms, availability, and eligibility vary by carrier and are governed by the policy as issued.
Get a Virginia motorcycle insurance quote
McEvoy Insurance & Financial Services is an independent agency in Alexandria, VA. Because we are independent we compare carriers for you. Read more about motorcycle insurance, or send us your details and we will come back to you with options.
Request a quoteor call (703) 642-6408
